
Everything about
NRI Private Family Trust Planning Made Simple and Structured
Our Private Trust Planning approach supports NRIs with family-focused guidance, structured asset management, and succession planning for seamless cross-border wealth transfer.
What is Private Family Trust?
A Private Family Trust can help Non-Resident Indians (NRIs) organise, manage, and plan the transfer of family wealth through a structured legal arrangement. For NRIs who own property, investments, business interests, or other assets in India, a trust may provide a framework for managing selected assets and providing for family members over time.
How we make Private Family Trust work better for you?
At Ashutosh Financial Services, we approach NRI Private Family Trust Planning by understanding your family circumstances, country of residence, asset ownership, beneficiary needs, and long-term wealth-transfer objectives. We help you evaluate relevant trust structures and coordinate the financial aspects of planning, while considering the legal, tax, FEMA, and cross-border requirements that may apply. The right trust arrangement depends on your objectives, the assets involved, the intended beneficiaries, and the laws that apply to your circumstances.

A Private Family Trust is a legal arrangement in which a person, known as the settlor, places eligible assets under the responsibility of a trustee for the benefit of specified beneficiaries. For NRIs, trust planning may involve Indian assets, overseas assets, or both. Before creating a trust, it is important to understand how the assets are owned, whether they can be transferred to the proposed trust, and how the arrangement may be treated under the relevant legal and tax rules.
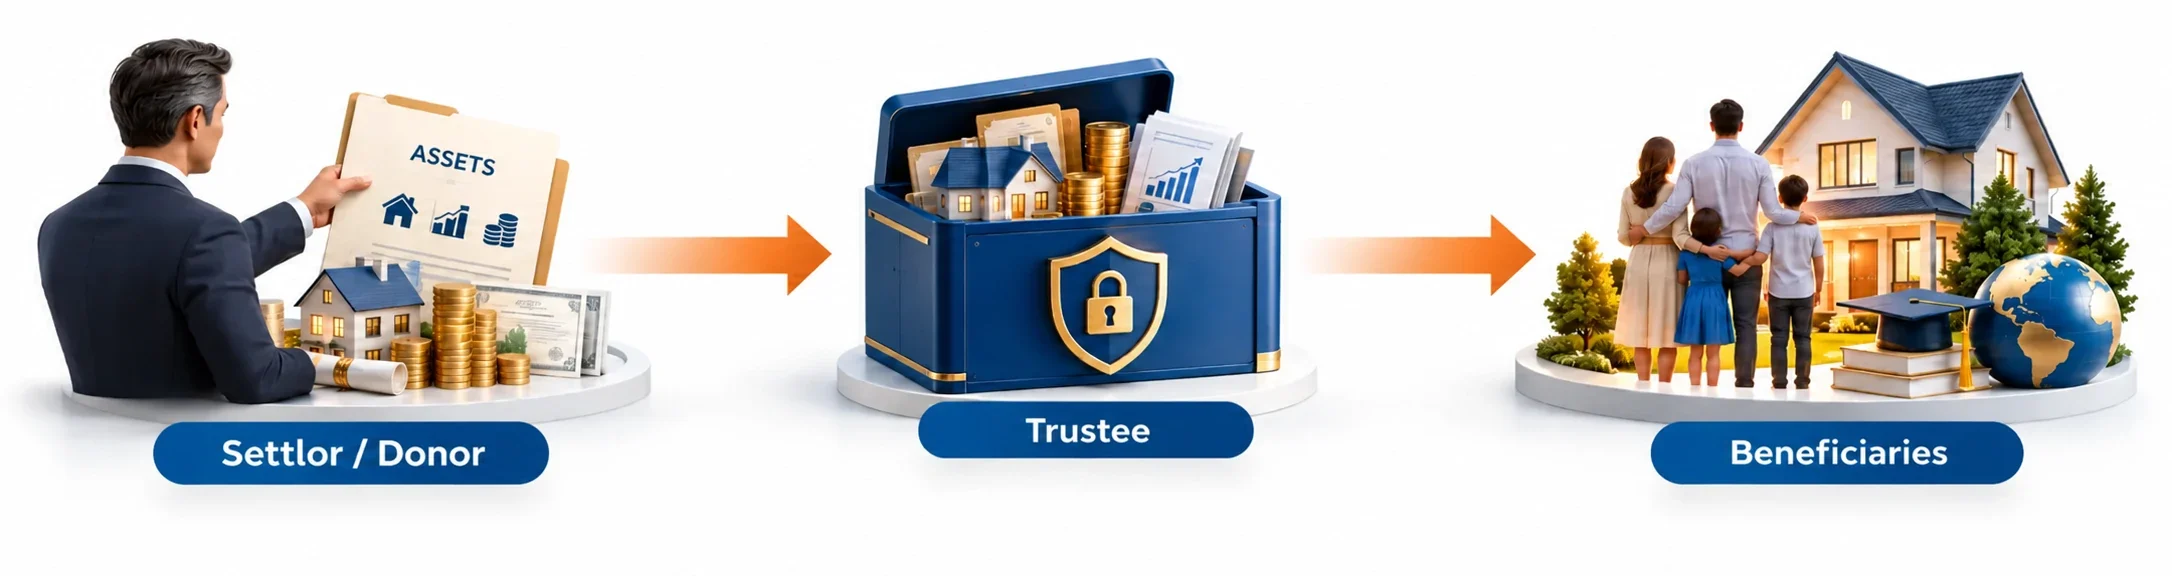
Settlor:The person who establishes the trust and settles eligible assets into it according to the trust deed.
Trustee: The person or entity responsible for holding, managing, and administering the trust assets in accordance with the trust deed and applicable law.
Beneficiary: The person or group of people intended to receive benefits from the trust, such as a spouse, children, grandchildren, or other specified family members.
Protector or Mentor: A trust deed may provide for a protector with specific oversight powers. The role and authority depend on the trust structure and the terms of the deed.

Revocable Trust: A trust that may allow the settlor to revoke or amend the arrangement, subject to its terms and applicable law. Retained powers can affect the legal and tax treatment of the trust.
Irrevocable Trust: A trust intended to place assets under a more lasting arrangement, with limited ability to revoke or change it. The available powers depend on the trust deed and applicable law.
Specific or Determinate Trust: A trust in which the beneficiaries and their respective entitlements are defined. This may help establish clarity about how benefits are allocated.
Discretionary Trust: A trust that gives the trustee discretion to distribute benefits among eligible beneficiaries within the powers and conditions set out in the trust deed.
Testamentary Trust: A trust created through a Will that generally takes effect after the testator’s death, subject to the Will and applicable succession law.
Lifetime Trust: A trust established during the settlor’s lifetime through the relevant trust instrument, subject to applicable legal requirements.
Structured Family Wealth Management: A trust can establish defined responsibilities for managing eligible assets, helping families organise their financial arrangements.
Planned Wealth Transfer: The trust deed can set out how and when beneficiaries may receive benefits, subject to its terms and applicable law.
Support for Family Members: A trust may be structured to provide for children’s education, a spouse’s financial needs, dependent family members, or other specified purposes.
Defined Distribution Conditions: Depending on the structure, distributions may be linked to specified ages, needs, events, or other conditions.
Continuity of Asset Administration: A trust can provide a continuing framework for administering its assets through appointed trustees, according to the trust deed.
Coordination of Family Assets: Trust planning can form part of a wider estate plan that considers property, investments, business interests, Wills, and other succession arrangements.
Planning for Families Across Countries: Where assets or beneficiaries are located in different countries, trust planning can help identify the legal and administrative matters that need to be coordinated
1
We begin by understanding why you are considering a Private Family Trust and what you want it to achieve for your family.
Your country of residence and relevant residential status
Your family responsibilities and intended beneficiaries
Your long-term wealth-transfer objectives
Your existing estate-planning arrangements
Your preferences for managing and distributing family assets
2
We help organise the relevant financial and ownership information required for trust-planning discussions.
Residential and commercial properties
Mutual funds, shares, bonds, and other investments
Bank deposits and other eligible financial assets
Business interests and other permitted assets
Existing Wills, nominations, and trust arrangements
Loans, liabilities, and jointly owned assets
3
We help you organise your intended beneficiaries and the financial support you wish to provide.
Identifying beneficiaries and their intended benefits
Planning for children, a spouse, parents, and other dependants
Defining distribution conditions, where appropriate
Considering future family needs and changing circumstances
Establishing how trustee responsibilities should be defined
4
The proposed trust structure should reflect your objectives, preferred level of control, and the needs of the beneficiaries.
Revocable or irrevocable arrangements
Specific or discretionary beneficiary entitlements
Lifetime or testamentary trust structures
Trustee responsibilities and powers
Flexibility to address future family circumstances
Relevant Indian and overseas legal considerations
5
Before assets are transferred, the potential legal, tax, and regulatory consequences should be assessed.
Legal requirements for creating the trust
Stamp duty, registration, and documentation requirements, where applicable
Tax treatment of the trust, its income, and distributions
FEMA and other regulatory requirements for relevant cross-border transactions
Implications of transferring property, investments, or business interests
Reporting or compliance requirements in the relevant countries
6
Once the structure and documentation have been reviewed, the trust can be established by completing the applicable formalities.
Preparing and executing the trust deed
Completing applicable stamping or registration formalities
Documenting the appointment and responsibilities of trustees
Completing required asset-transfer procedures
Arranging relevant banking and administrative processes
Maintaining records of the assets settled into the trust
7
A Private Family Trust may require review as family circumstances, assets, and legal requirements change.
Changes in family circumstances or beneficiaries
Changes in the country of residence of the settlor, trustees, or beneficiaries
Acquisition or disposal of significant assets
Changes in tax, succession, or regulatory requirements
Trustee responsibilities and trust administration
Continued alignment with the family’s long-term objectives
Other service providers bill you separately for each service, making you pay more at extra costs.


Achieving financial stability begins with the right advice. Our experienced advisors help you identify suitable investment opportunities, manage risks, and create a clear strategy for long-term financial growth.

Find quick answers to common questions about our services, processes, and financial solutions.
A private trust is a legal arrangement in which a settlor places assets under the responsibility of a trustee for the benefit of specified beneficiaries. The trustee administers the assets according to the trust deed and applicable law.
A person who is legally competent to create a trust may establish one, subject to the requirements of the Indian Trusts Act, 1882, where applicable, and other relevant laws. The appropriate structure depends on the nature of the assets, the trust's purpose and the parties involved.
A revocable trust allows the settlor to retain specified powers to revoke or amend the arrangement. An irrevocable trust is generally intended not to be freely revoked once it takes effect. The distinction can affect control over assets and their legal and tax treatment.
Depending on the trust structure and applicable law, assets may include property, investments, bank deposits, shares and certain business interests. Each transfer must comply with the relevant ownership, documentation, registration and regulatory requirements.
A private trust and a Will serve different purposes. A trust can provide for the management and distribution of assets under its terms, while a Will generally sets out instructions for distributing an estate after death. The appropriate choice depends on your objectives, assets and family circumstances. Both may be used together where suitable.
A clearly drafted trust deed can establish responsibilities, beneficiary entitlements and distribution conditions, potentially reducing uncertainty. However, a trust cannot guarantee that disputes will be avoided.
Tax treatment depends on the trust's structure, the nature of the assets, the transfer arrangements, the type of income and the beneficiaries' entitlements. A private trust does not automatically provide tax exemption. Obtain a case-specific review from a qualified tax professional before establishing the trust.
The ability to amend, revoke or terminate a trust depends on its terms, the applicable law and the type of trust. The trust deed should be reviewed carefully before execution.
Registration and other formalities depend on the type of trust, the assets involved and the applicable laws. For example, a trust involving immovable property may have specific written-instrument, stamping and registration requirements. Obtain legal advice before transferring assets.
Ashutosh Financial Services helps families understand private trust structures, organise relevant financial information and evaluate their estate-planning objectives. Legal drafting, trust formation and tax implementation should be handled or reviewed by appropriately qualified professionals.
A private trust is a legal arrangement in which a settlor places assets under the responsibility of a trustee for the benefit of specified beneficiaries. The trustee administers the assets according to the trust deed and applicable law.
A person who is legally competent to create a trust may establish one, subject to the requirements of the Indian Trusts Act, 1882, where applicable, and other relevant laws. The appropriate structure depends on the nature of the assets, the trust's purpose and the parties involved.
Depending on the trust structure and applicable law, assets may include property, investments, bank deposits, shares and certain business interests. Each transfer must comply with the relevant ownership, documentation, registration and regulatory requirements.
A private trust and a Will serve different purposes. A trust can provide for the management and distribution of assets under its terms, while a Will generally sets out instructions for distributing an estate after death. The appropriate choice depends on your objectives, assets and family circumstances. Both may be used together where suitable.
A revocable trust allows the settlor to retain specified powers to revoke or amend the arrangement. An irrevocable trust is generally intended not to be freely revoked once it takes effect. The distinction can affect control over assets and their legal and tax treatment.
A clearly drafted trust deed can establish responsibilities, beneficiary entitlements and distribution conditions, potentially reducing uncertainty. However, a trust cannot guarantee that disputes will be avoided.
Tax treatment depends on the trust's structure, the nature of the assets, the transfer arrangements, the type of income and the beneficiaries' entitlements. A private trust does not automatically provide tax exemption. Obtain a case-specific review from a qualified tax professional before establishing the trust.
The ability to amend, revoke or terminate a trust depends on its terms, the applicable law and the type of trust. The trust deed should be reviewed carefully before execution.
Registration and other formalities depend on the type of trust, the assets involved and the applicable laws. For example, a trust involving immovable property may have specific written-instrument, stamping and registration requirements. Obtain legal advice before transferring assets.
Ashutosh Financial Services helps families understand private trust structures, organise relevant financial information and evaluate their estate-planning objectives. Legal drafting, trust formation and tax implementation should be handled or reviewed by appropriately qualified professionals.
Disclaimer: Clicking a login button will redirect you to an external portfolio platform.

