
Secure Your Legacy with Smarter Estate Planning
Our NRI Estate Planning approach helps protect global assets, preserve wealth, and secure your legacy for future generations.

What is Estate planning?
Estate planning helps you organise, protect, and transfer your wealth across countries according to your wishes. It involves planning for assets such as property, investments, bank accounts, and other holdings while considering the applicable legal, tax, and succession requirements in India and your country of residence. A well-structured estate plan can help reduce uncertainty, simplify the transfer of assets, and protect your family’s financial interests for the future.
How we make Estate planning work better for you?
At Ashutosh Financial Services, we help NRIs understand estate planning options based on their assets, family circumstances, and long-term objectives. Our approach focuses on wealth preservation, succession planning, and intergenerational wealth transfer, helping you plan for the orderly transfer of assets and preserve your financial legacy. Where required, coordination with appropriate legal and tax professionals can help address cross-border requirements.
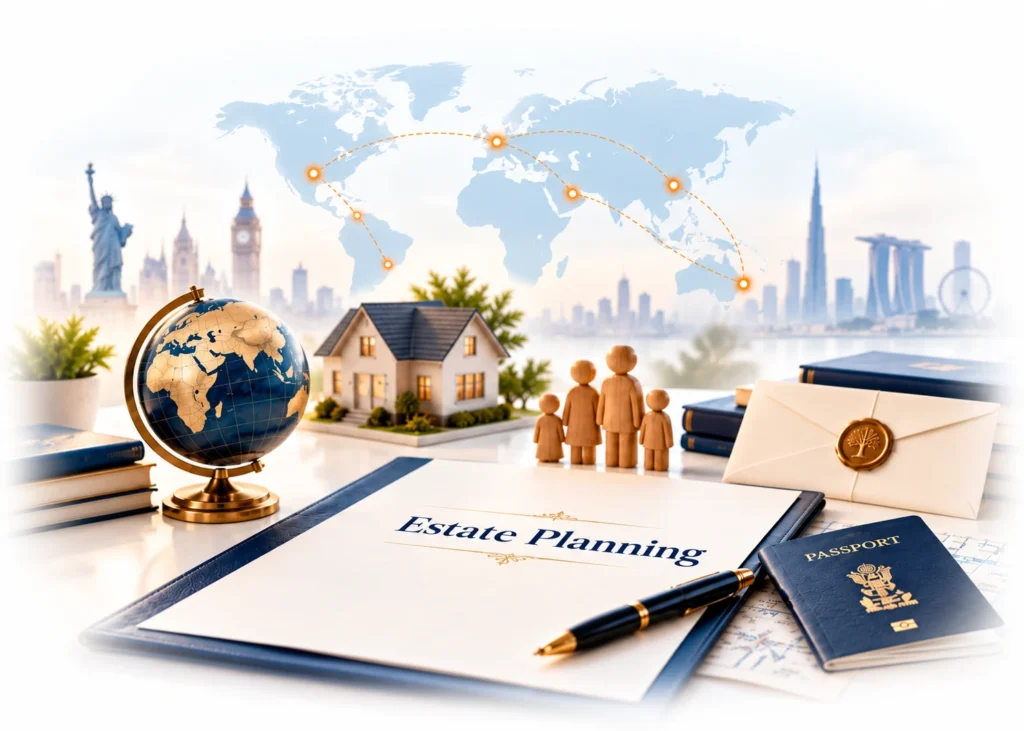
We connect estate planning with your broader financial journey, helping protect accumulated wealth, prepare for succession, and support your family's financial future through a structured, personalized strategy..
Secure your family’s future with professionally structured wills that protect your assets, honour your wishes, and ensure a smooth legacy transfer.
›Protect and preserve family wealth with private family trusts designed for effective asset management, succession planning, and long-term financial security.
›NRI estate planning helps Non-Resident Indians (NRIs) protect, manage, and transfer their assets across different countries in a structured and tax-efficient manner. It ensures smooth wealth succession, minimizes legal and tax complications, reduces the risk of family disputes, and provides financial security for future generations while ensuring compliance with the applicable laws of the countries involved.
If an NRI owns assets in India, it is important to plan who should receive those assets and how they should be transferred after death. The succession of Indian assets broadly depends on whether the person has left behind a valid Will. A properly planned Will can therefore provide clarity regarding who should receive the assets and how they should be distributed after the person’s death.
For an NRI, succession of assets located outside India generally depends on the type of asset and the law applicable in the relevant country.
Immovable Assets: Assets such as a house, land or other property situated outside India are generally governed by the succession laws of the country where the property is located. For example, property in the UK or US would be subject to the applicable local succession and probate laws of that jurisdiction.
Movable Assets: Assets such as overseas bank accounts, securities and other financial assets are generally governed by the law of the deceased’s domicile at the time of death. For example, if an NRI was domiciled in the US at the time of death, the law of that domicile may govern the succession of movable assets, even where such movable assets are held in more than one country.
1
We begin by understanding your financial position across India and your country of residence to establish a clear foundation for your estate plan.
Key areas of review:
2
We review your existing estate arrangements to identify gaps and understand how Indian and foreign laws may affect the ownership, succession, and transfer of your assets.
Key areas of review:
3
We outline a structured approach to organising your global wealth and documenting your wishes, taking into account your family objectives and applicable jurisdictional requirements.
Key planning considerations:
4
We coordinate with relevant legal, tax, and financial professionals in the applicable jurisdictions to support the preparation and review of your estate planning documents.
Key areas of coordination:
5
We recommend periodic reviews to ensure your estate plan remains aligned with your global assets, family circumstances, residency, and applicable laws.
Key review triggers:
Other service providers bill you separately for each service, making you pay more at extra costs.


Achieving financial stability begins with the right advice. Our experienced advisors help you identify suitable investment opportunities, manage risks, and create a clear strategy for long-term financial growth.

Find quick answers to common questions about our services, processes, and financial solutions.
NRI estate planning is the process of organising Indian and overseas assets and establishing appropriate arrangements for their management and succession, considering family objectives, applicable succession laws, taxation and regulatory requirements.
Global Indians may hold assets in multiple countries and have family members living in different jurisdictions. A structured estate plan can help document succession intentions and coordinate wills, nominations, trusts and asset ownership.
Ashutosh Financial Services combines estate planning with its broader NRI financial-services framework, including investments, insurance, taxation, FEMA and international-tax considerations. This helps the family's estate be viewed as part of its overall financial structure.
A will can provide a structured way to express testamentary intentions regarding assets covered by it. Whether a separate will is appropriate for Indian and overseas assets depends on the individual's circumstances and the laws of the relevant jurisdictions.
An NRI can generally make testamentary arrangements concerning Indian assets, subject to applicable succession law and the specific circumstances. The drafting and execution should be reviewed appropriately, particularly where assets and beneficiaries span multiple jurisdictions.
No. Nomination and succession are distinct concepts. A nomination can facilitate administration or receipt of an asset according to the governing framework, but it should not automatically be treated as a complete substitute for a will or broader succession planning.
A private trust may be considered for certain family wealth and succession objectives, subject to the applicable legal and tax framework. Its suitability depends on the assets, beneficiaries, objectives and structure.
NRIs and OCIs can inherit certain immovable property in India subject to applicable law and FEMA provisions. RBI's regulations specifically address inheritance of immovable property by NRIs and OCIs.
It can. Indian taxation and the tax laws of the NRI's country of residence may both need consideration. The tax treatment depends on the assets, transaction, succession structure and applicable laws.
The plan should be reviewed after significant changes such as marriage, divorce, birth of a child, death of a beneficiary, major asset acquisition, change in country of residence, creation of a business, establishment of a trust or significant changes in wealth.
NRI estate planning is the process of organising Indian and overseas assets and establishing appropriate arrangements for their management and succession, considering family objectives, applicable succession laws, taxation and regulatory requirements.
Global Indians may hold assets in multiple countries and have family members living in different jurisdictions. A structured estate plan can help document succession intentions and coordinate wills, nominations, trusts and asset ownership.
A will can provide a structured way to express testamentary intentions regarding assets covered by it. Whether a separate will is appropriate for Indian and overseas assets depends on the individual's circumstances and the laws of the relevant jurisdictions.
An NRI can generally make testamentary arrangements concerning Indian assets, subject to applicable succession law and the specific circumstances. The drafting and execution should be reviewed appropriately, particularly where assets and beneficiaries span multiple jurisdictions.
Ashutosh Financial Services combines estate planning with its broader NRI financial-services framework, including investments, insurance, taxation, FEMA and international-tax considerations. This helps the family's estate be viewed as part of its overall financial structure.
No. Nomination and succession are distinct concepts. A nomination can facilitate administration or receipt of an asset according to the governing framework, but it should not automatically be treated as a complete substitute for a will or broader succession planning.
A private trust may be considered for certain family wealth and succession objectives, subject to the applicable legal and tax framework. Its suitability depends on the assets, beneficiaries, objectives and structure.
NRIs and OCIs can inherit certain immovable property in India subject to applicable law and FEMA provisions. RBI's regulations specifically address inheritance of immovable property by NRIs and OCIs.
It can. Indian taxation and the tax laws of the NRI's country of residence may both need consideration. The tax treatment depends on the assets, transaction, succession structure and applicable laws.
The plan should be reviewed after significant changes such as marriage, divorce, birth of a child, death of a beneficiary, major asset acquisition, change in country of residence, creation of a business, establishment of a trust or significant changes in wealth.
Disclaimer: Clicking a login button will redirect you to an external portfolio platform.

